Does Car Insurance Cover a Rental Car on Vacation?
Does car insurance cover a rental car on vacation? Your policy may extend collision and liability coverage, but gaps for loss-of-use fees can cost you.
By Julia Owens
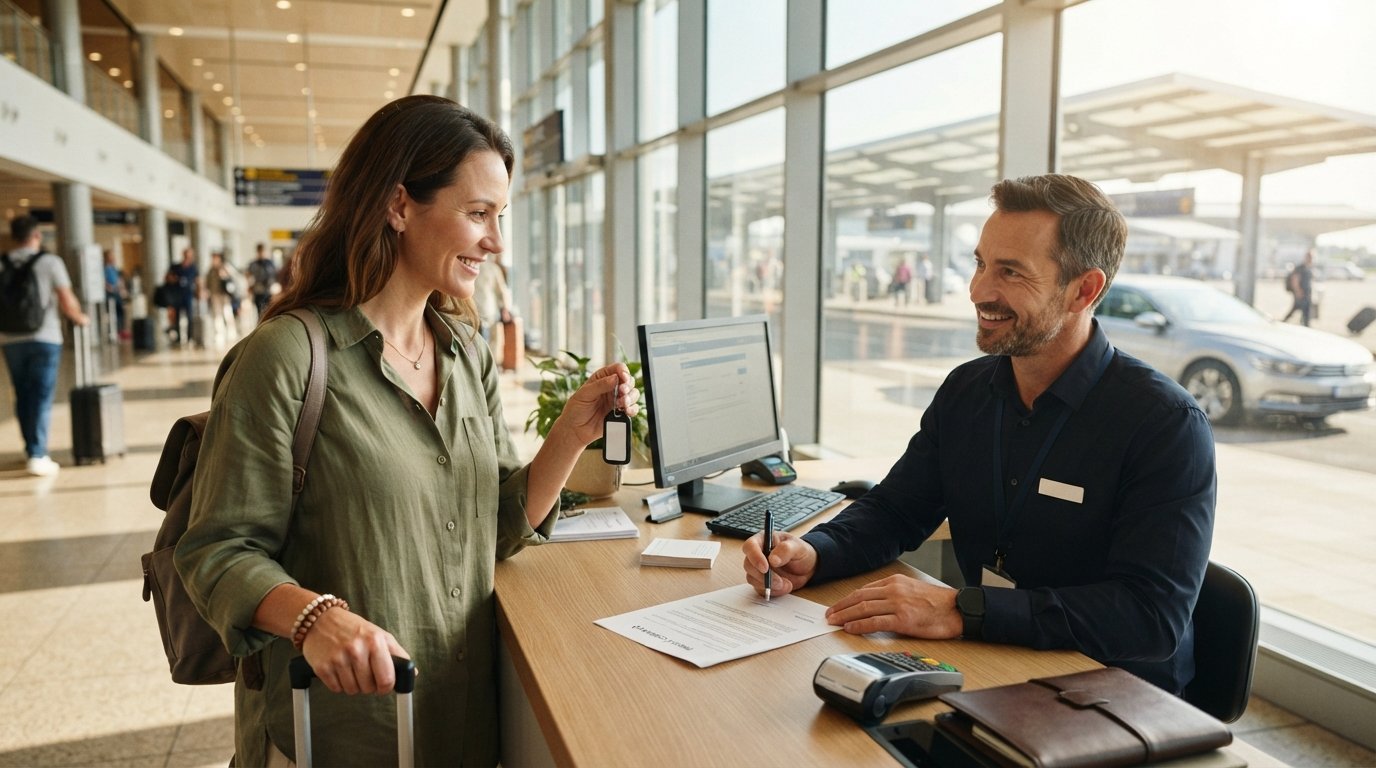
You step off the plane, grab your bags, and head to the rental counter. The agent slides a contract across the desk and asks the question that has derailed countless vacation budgets: "Do you want to add our collision damage waiver for $34.95 a day?" You pause, trying to remember whether your personal auto policy already protects you here. The answer is not a simple yes or no, and getting it wrong can cost you hundreds or even thousands of dollars in surprise fees. Understanding how your personal car insurance interacts with a rental car on vacation is one of the most valuable pieces of travel knowledge you can have, and it starts with a close look at your own policy declarations page.
How Personal Auto Policies Extend to Rental Cars
In most U.S. states, a personal auto insurance policy follows you, not just your car. That means when you rent a vehicle for personal use, the liability, collision, and comprehensive coverage on your own policy typically extends to that rental, subject to your policy limits and deductibles. This is the core reason many travelers can decline the rental company's expensive add-ons and still drive off the lot with confidence. However, the extension is not universal, and it comes with conditions that vary by insurer and by state.
The first thing to verify is whether your policy includes collision and comprehensive coverage at all. If you only carry liability insurance (the minimum required in most states), your policy will not pay to repair or replace a damaged rental car. You need to see both collision and comprehensive listed on your declarations page, or a combined "full coverage" designation, before you can rely on your policy for physical damage to the rental. Your deductible still applies, so if you have a $1,000 deductible, you would pay that amount out of pocket before your insurer covers the rest of the repair bill.
It is also important to understand that your policy's coverage extends only for personal use and typically only for rentals that meet certain vehicle classifications. Most standard policies cover passenger cars, SUVs, and minivans, but they may exclude large vans, trucks, exotic cars, or vehicles rented for business purposes. If you plan to rent a specialty vehicle or use it for work, call your insurer before you book. The last thing you want is to discover a coverage gap after an accident on a winding mountain road.
Checking Your Declarations Page Before You Travel
Before any vacation, take five minutes to review your auto policy's declarations page. Look specifically for collision and comprehensive coverage, your deductible amounts, and any endorsements related to rental vehicles. Some insurers offer a rental car endorsement that extends coverage with higher limits or fills specific gaps, and it may be worth adding if you rent frequently. If your policy is vague or you cannot find the information, call your agent and ask directly: "Does my policy cover a rental car on vacation, and what are the limits?" Getting that answer in writing or at least confirming it verbally gives you a paper trail if a claim dispute arises later.
Where Liability Coverage Applies and Where It Stops
Liability coverage is the portion of your policy that pays for damage you cause to other people or their property. When you rent a car, your personal liability coverage generally extends to the rental, meaning if you rear-end another vehicle, your policy should respond up to your liability limits. This is a critical protection because rental companies typically provide only the state minimum liability coverage, which can be dangerously low. If you cause a serious accident with injuries, state minimum limits may not be enough to cover the damages, and you could be personally responsible for the excess.
However, liability coverage has boundaries. Your policy's limits apply per accident, and if the rental car is in a state with different financial responsibility laws, the minimum requirements may differ from your home state. More importantly, your personal liability coverage does not protect the rental car itself. If you damage the rental vehicle, that falls under collision and comprehensive coverage, not liability. This distinction trips up many travelers who assume "full coverage" means everything is handled. In reality, you need both liability and physical damage coverage to be fully protected in a rental scenario.
Another limitation involves who is driving. Your policy typically covers you and any listed drivers on your policy, but it may not cover additional drivers you add at the rental counter unless they are also listed on your auto policy. If you plan to share driving duties with a friend or family member who is not on your policy, verify whether your insurer extends coverage to permissive drivers of a rental car. Some do, some do not, and the rental company's own restrictions may add another layer of complexity.
When Credit Cards and Travel Policies Fill the Gap
Many major credit cards offer rental car collision damage waivers as a cardholder benefit. This is not insurance in the traditional sense, but it can reimburse you for damage to or theft of a rental car if you decline the rental company's collision damage waiver and pay for the rental with that card. This benefit can be a valuable backstop, especially if your personal auto policy has a high deductible or excludes rental coverage. However, credit card benefits come with strict conditions that vary widely by card issuer and card tier.
Common requirements include paying for the entire rental with the card, declining the rental company's collision damage waiver, renting for a limited number of days (often 15 to 31 days), and renting in the country where the card is issued. Some cards exclude certain vehicle types, such as luxury cars, vans, or trucks, and many exclude rentals in specific countries like Israel, Jamaica, or Ireland. The benefit typically covers physical damage and theft but not liability, personal injury, or loss of use fees unless specifically stated. You must also report the incident to the card issuer promptly and provide documentation, which can be a paperwork burden during an otherwise relaxing vacation.
Travel insurance policies may also include rental car coverage, either as a standalone benefit or as part of a comprehensive travel insurance package. These policies can fill gaps left by your auto insurer or credit card, but they often come with their own deductibles, exclusions, and claim processes. The key is to read the fine print before you leave home and understand exactly what is covered, what is excluded, and what steps you must take if something goes wrong. Relying on a patchwork of coverage without understanding each piece is a recipe for confusion at the worst possible moment.
Comparing Coverage Sources Side by Side
To make an informed decision, it helps to compare your potential coverage sources directly. Consider these factors for your personal auto policy, your credit card, and any travel insurance you might purchase:
- Primary vs. secondary coverage: Some credit cards provide primary coverage, meaning they pay first without involving your auto insurer. Others provide secondary coverage, which only pays after your auto insurance has paid its share. Primary coverage is generally more valuable because it avoids a claim on your auto policy.
- Deductibles and limits: Your auto policy deductible applies to rental claims, while credit card benefits often have no deductible but may cap coverage at a specific amount, such as $50,000 or the actual cash value of the rental.
- Excluded vehicles and countries: Both auto policies and credit cards may exclude certain vehicle types and rental locations. Check these lists carefully if your itinerary includes a cargo van, a luxury convertible, or a rental in a foreign country.
- Loss of use and administrative fees: Rental companies may charge you for the income they lost while the car was being repaired (loss of use) and for administrative costs. Some credit cards and auto policies cover these fees; others do not.
Understanding these differences helps you decide whether to rely on your existing coverage, add a rental car endorsement to your auto policy, or purchase supplemental protection. There is no single right answer for every traveler, but there is a right answer for your specific situation, and it depends on your policy, your card, and your destination.
Loss-of-Use and Administrative Fees: The Hidden Costs
Even when your insurance covers the physical damage to a rental car, you may still face charges that are not covered. Rental companies commonly charge loss-of-use fees, which represent the revenue they lost while the vehicle was out of service for repairs. They may also charge administrative fees for processing the claim, and these can add up to hundreds of dollars. Whether your auto policy or credit card covers these fees depends on the specific terms of your coverage.
Some auto insurers cover loss-of-use and administrative fees as part of a rental claim, but others exclude them or apply them against your policy limits. Credit card benefits vary even more widely; some explicitly cover loss of use and administrative fees, while others do not. If you decline the rental company's collision damage waiver and rely on your own coverage, you could be on the hook for these fees even if the damage itself is covered. This is one of the strongest arguments for purchasing the rental company's waiver in certain situations, especially if your own coverage is uncertain or has significant gaps.
It is also worth noting that rental companies may charge a diminished value fee, claiming that the vehicle is worth less after being repaired. This is another charge that may or may not be covered by your insurance or credit card. The best defense is to inspect the rental car carefully before you drive off the lot, document any existing damage with photos and a written report, and return the car in the same condition. If an incident does occur, report it immediately to the rental company, your insurer, and your credit card issuer, and keep copies of all documentation.
Why Coverage Varies by State and Rental Location
Insurance is regulated at the state level, which means the rules that govern how your policy extends to a rental car can differ depending on where you live and where you rent. Some states require insurers to extend coverage to rental cars, while others allow insurers to exclude or limit that coverage. Your policy's terms are also shaped by the state where it was issued, so a policy purchased in Texas may behave differently in California or Florida. This is why it is essential to read your policy and confirm coverage before you travel, rather than assuming that what works at home will work everywhere.
Rental company practices also vary by location. Some rental companies are more aggressive about requiring proof of insurance or selling their own coverage, while others are more relaxed. In some countries, your U.S. auto policy may provide no coverage at all, and your credit card benefit may exclude that country entirely. If you are renting abroad, you may need to purchase local insurance or rely on a travel insurance policy that specifically covers international rentals. The key is to research your destination and rental company before you book, not after you arrive at the counter.
For consumers who want to compare auto insurance options and understand how different policies handle rental cars, resources like this insurance shopping resource can provide useful guidance. Comparing quotes and reading policy details side by side is one of the most effective ways to ensure you have the coverage you need, both at home and on the road. Whether you are shopping for a new policy or reviewing your current one, taking the time to understand rental car coverage can save you money and stress on your next vacation.
Practical Steps to Protect Yourself on Your Next Trip
Before you leave for vacation, take a few practical steps to confirm your coverage and avoid surprises at the rental counter. Start by reviewing your auto policy's declarations page and confirming that collision and comprehensive coverage are active. Check your deductible and consider whether a lower deductible would be worth the additional premium. Then, review your credit card benefits and understand whether the card provides primary or secondary rental coverage, what vehicles and countries are excluded, and what steps you must take if an incident occurs.
If your coverage is uncertain or has significant gaps, consider purchasing the rental company's collision damage waiver or a supplemental policy. While it adds to the cost of your trip, it also adds peace of mind, especially if you are renting in a foreign country or driving an unfamiliar vehicle. For many travelers, the decision comes down to a simple calculation: the cost of the waiver versus the potential cost of an uncovered claim. If you have a high deductible, limited coverage, or a rental in a country where your card benefit does not apply, the waiver may be worth the expense.
Finally, document everything. Take photos of the rental car before you drive away, note any existing damage on the rental agreement, and keep copies of your insurance card and credit card benefit information with you. If an incident occurs, report it promptly and follow the claim procedures for each coverage source. Being prepared and informed turns a potentially stressful situation into a manageable one, and it lets you focus on what really matters: enjoying your vacation.
Understanding whether your car insurance covers a rental car on vacation is not just a matter of saving money at the counter. It is a matter of knowing your rights, your limits, and your options before you need them. With a little preparation, you can drive off the lot with confidence, knowing that you have made an informed decision about your coverage and that you are protected no matter what the road throws at you.