High Deductible vs Low Premium Insurance: Which Saves More?
High deductible vs low premium insurance which saves more depends on your emergency fund and claims risk. Run the break-even math before you choose.
By Patrick Parker
Choosing an insurance policy often comes down to a tug-of-war between two numbers: the monthly premium you pay and the deductible you agree to cover before benefits kick in. The question of high deductible vs low premium insurance which saves more is one of the most practical financial decisions you will make, yet it is frequently oversimplified by marketing pitches that promise rock-bottom rates without explaining the risk you are accepting. The truth is that neither option is universally superior. The right answer depends on your cash reserves, your tolerance for risk, your claims history, and the specific type of coverage you are buying.
This guide breaks down the real math behind the premium-deductible trade-off across auto, home, and health insurance. You will learn how to calculate your break-even point, why an emergency fund is the hidden variable in every high-deductible decision, and how your choice today can influence your pricing for years to come. By the end, you will have a framework that lets you compare quotes with confidence rather than guesswork. If you want to run real numbers against live offers, a comparison tool like QuoteComparison can put competing quotes side by side so the math becomes concrete.
How the Premium-Deductible Trade-Off Actually Works
Every insurance contract is a risk-sharing arrangement. You agree to absorb a fixed amount of loss (the deductible), and the insurer agrees to cover costs above that threshold in exchange for your premium. When you choose a higher deductible, you are essentially telling the insurer you will handle more of the small and medium claims yourself. That reduces the insurer's administrative and payout costs, and those savings get passed back to you as a lower monthly premium. When you choose a lower deductible, you pay more each month for the comfort of knowing a surprise expense will be largely covered.
This trade-off appears in every major insurance line, but the mechanics differ. In auto insurance, a common choice is between a $500 deductible and a $1,000 or $2,000 deductible. The premium difference might be $15 to $40 per month depending on your driving record, vehicle, and state. In home insurance, deductibles are often expressed as a flat dollar amount or a percentage of dwelling coverage, and moving from a $1,000 to a $2,500 deductible can shave 10 to 25 percent off your annual premium. Health insurance is the most dramatic example: a bronze-tier plan with a $7,000 deductible may cost hundreds less per month than a gold-tier plan with a $1,500 deductible, but the out-of-pocket exposure is vastly different.
What matters is that the trade-off is not linear. Doubling your deductible from $500 to $1,000 might save you 12 percent on premiums, while doubling it again from $1,000 to $2,000 might save only another 8 percent. Insurers price the first layer of risk most aggressively because small claims are frequent. Once you move into higher deductible territory, the marginal savings shrink. Understanding this curve helps you avoid over-insuring the small stuff while still protecting against catastrophic loss.
Running the Break-Even Math: Premium Savings vs. Out-of-Pocket Exposure
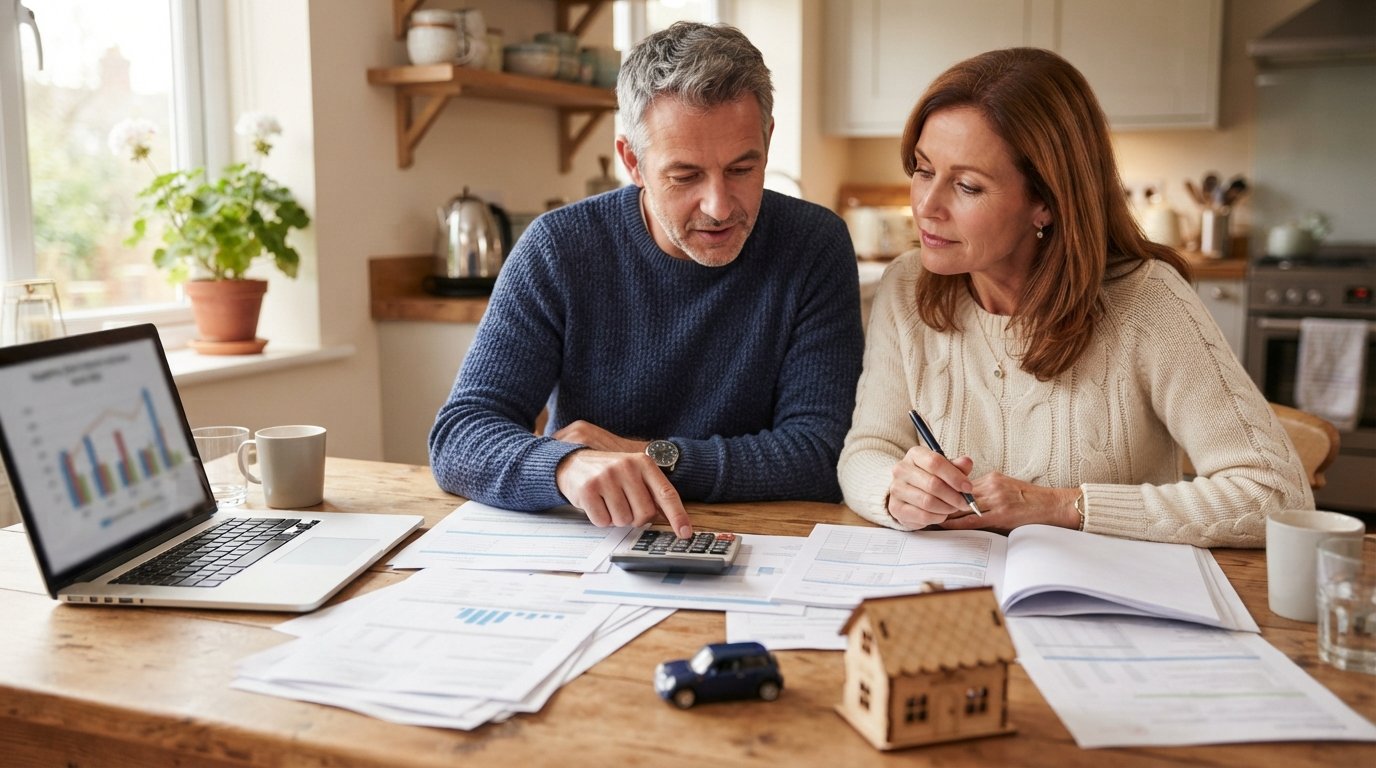
The core of the high deductible vs low premium insurance which saves more debate is a simple break-even calculation. You need to know how much you save each year by choosing the higher deductible, then compare that savings to the additional amount you would pay out of pocket if you file a claim. The formula is straightforward: divide the difference in deductibles by the annual premium savings. The result tells you how many years of premium savings it would take to offset the extra deductible exposure.
Here is a practical example for auto insurance. Suppose a low-deductible policy with a $500 deductible costs $1,800 per year, while a high-deductible policy with a $2,000 deductible costs $1,440 per year. The annual premium savings is $360, and the additional deductible exposure is $1,500. Dividing $1,500 by $360 gives roughly 4.2 years. If you go five years without a claim, you come out ahead with the high-deductible plan. If you file a claim in year one, you lose money compared to the low-deductible option. The break-even math forces you to think about your claims probability, not just your monthly payment.
For health insurance, the math is more complex because deductibles interact with copays, coinsurance, and out-of-pocket maximums. A high-deductible health plan may save you $3,000 per year in premiums, but if you have a chronic condition requiring regular care, you could hit the deductible quickly and face thousands in out-of-pocket costs before coinsurance kicks in. On the other hand, if you are generally healthy and only need preventive care (which is often covered at no cost), the premium savings can be substantial. The key is to model your expected annual healthcare spending, not just your best-case scenario.
To make this concrete, here is a simple three-step framework you can apply to any policy comparison:
- Calculate annual premium savings: Subtract the high-deductible premium from the low-deductible premium and multiply by 12 if the quotes are monthly.
- Calculate additional deductible exposure: Subtract the low deductible from the high deductible.
- Divide exposure by savings: The result is your break-even period in years. If you expect to go longer than that without a claim, the high-deductible plan likely saves more.
This framework is not a guarantee, because claims are unpredictable. But it gives you a rational basis for choosing rather than relying on the vague feeling that lower monthly payments are always better. It also highlights why the answer to high deductible vs low premium insurance which saves more changes depending on the policy type and your personal risk profile.
Emergency Fund Considerations Before Choosing a High Deductible
The single most important prerequisite for choosing a high-deductible plan is a fully funded emergency fund. If you cannot comfortably pay your deductible tomorrow without borrowing, you are taking on risk you cannot afford. The entire logic of the high-deductible strategy depends on your ability to absorb the worst-case out-of-pocket cost without financial strain. Without that cushion, a single accident or illness could wipe out the premium savings you accumulated over years.
How much should you set aside? At a minimum, your emergency fund should cover your deductible plus a reasonable buffer for related expenses. For auto insurance, a $2,000 deductible means you need at least $2,000 accessible, but you should also account for rental car costs, towing, and any gaps in coverage. For home insurance, a 2 percent deductible on a $400,000 home is $8,000, which is a significant sum. For health insurance, your out-of-pocket maximum is the real number to plan for, not just the deductible, because coinsurance can add thousands more after the deductible is met.
Here is a practical checklist to evaluate whether you are ready for a high deductible:
- You have at least the full deductible amount in a liquid savings account.
- You could cover the deductible and still meet your regular monthly obligations for at least three months.
- You have no high-interest debt that would be exacerbated by an unexpected expense.
- You have a stable income and reasonable confidence in your job security.
- You understand that the deductible applies per claim or per year, depending on the policy.
If you cannot check most of these boxes, a lower deductible with a higher premium is the more responsible choice, even if it costs more each month. The purpose of insurance is to protect against financial ruin, not to optimize every dollar. A high-deductible plan that leaves you unable to pay for a claim is not a savings strategy; it is a false economy.
How Deductible Choices Affect Claims Behavior and Long-Term Pricing
Your deductible choice does more than determine your monthly bill. It shapes your behavior when something goes wrong, and that behavior can influence your long-term insurance costs. When you carry a high deductible, you are more likely to pay small repairs out of pocket rather than filing a claim. This is often the right financial decision, because filing frequent small claims can flag you as a high-risk policyholder and lead to premium increases or even non-renewal. Insurers track claims frequency, not just severity, and a pattern of small claims can cost you more in the long run than the claims themselves.
On the other hand, a low deductible encourages you to file claims for smaller incidents because the insurer is covering most of the cost. That can be convenient, but it can also create a claims history that follows you. In auto insurance, for example, a single at-fault claim can raise your premium by 20 to 40 percent for three to five years. If you filed a $900 claim with a $500 deductible, you might receive $400 from the insurer but pay far more than that in increased premiums over the next few years. A high deductible forces you to think twice before filing, which often aligns with your long-term financial interest.
There is also a pricing dynamic at play. Insurers increasingly use sophisticated data to segment risk. Policyholders who choose high deductibles are often statistically safer drivers or homeowners because they have skin in the game and are motivated to avoid claims. Some carriers offer additional discounts or preferred pricing tiers for policyholders who demonstrate responsible claim behavior. While the effect is not universal, it is another reason why the cheapest premium is not always the cheapest policy, and the most expensive premium is not always the best value. The goal is to find the deductible level that matches your risk tolerance and financial capacity, then compare quotes from multiple carriers to ensure you are getting a fair price for that choice.
Situations Where a Lower Deductible Is Worth the Higher Premium
Despite the appeal of lower monthly payments, there are clear situations where paying more for a lower deductible is the smarter financial move. The first is when your emergency fund is thin or nonexistent. If you are living paycheck to paycheck, a high deductible is a gamble you cannot afford to lose. The premium savings might feel good each month, but a single claim could force you into credit card debt or a personal loan, wiping out any savings and then some.
The second situation is when you have a known, elevated risk of claims. If you live in an area prone to hail, wildfires, or flooding, or if you have a teenage driver on your auto policy, the probability of filing a claim is higher. In those cases, the break-even period for a high deductible may be shorter than your likely time between claims, making the low-deductible option more cost-effective. Similarly, if you have a chronic health condition or are planning a surgery or pregnancy, a health plan with a lower deductible and higher premium may save you thousands in out-of-pocket costs over the course of the year.
The third situation is when the premium difference is small. Sometimes the gap between a $500 deductible and a $1,000 deductible is only a few dollars per month. In that case, the break-even period could be a decade or more, and the low-deductible plan is almost certainly the better value. You should always run the math rather than assuming that high deductible equals high savings. The answer to high deductible vs low premium insurance which saves more is highly sensitive to the specific numbers in front of you.
Finally, consider your personal psychology. Some people sleep better at night knowing that a major expense is largely covered. If the anxiety of a high deductible would lead you to avoid necessary care or repairs, the lower deductible is worth the premium. Insurance is not just a financial product; it is a tool for managing risk and uncertainty. The best policy is the one that protects both your wallet and your peace of mind.
When you are ready to compare specific quotes, whether for auto, home, health, or life coverage, using a comparison service can save you hours of legwork. You can also explore strategies to reduce costs without sacrificing coverage, such as the tactics covered in our guide on how to lower car insurance premiums without changing coverage. Combining deductible optimization with other savings levers, like bundling and safe-driver discounts, is often the most effective way to reduce your overall insurance spend while maintaining adequate protection.
The decision between a high deductible and a low premium is not about finding a universal answer. It is about matching the structure of your policy to the realities of your financial life. Run the break-even math, confirm your emergency fund can handle the worst case, and consider how your claims behavior might affect your pricing over time. When you approach the choice with that framework, you can stop guessing and start saving with confidence.