Home Insurance in Hurricane and Wildfire Zones: What to Expect
Home insurance in hurricane and wildfire zones what to expect: percentage deductibles, flood exclusions, and FAIR plan options that protect your recovery.
By Patrick Parker
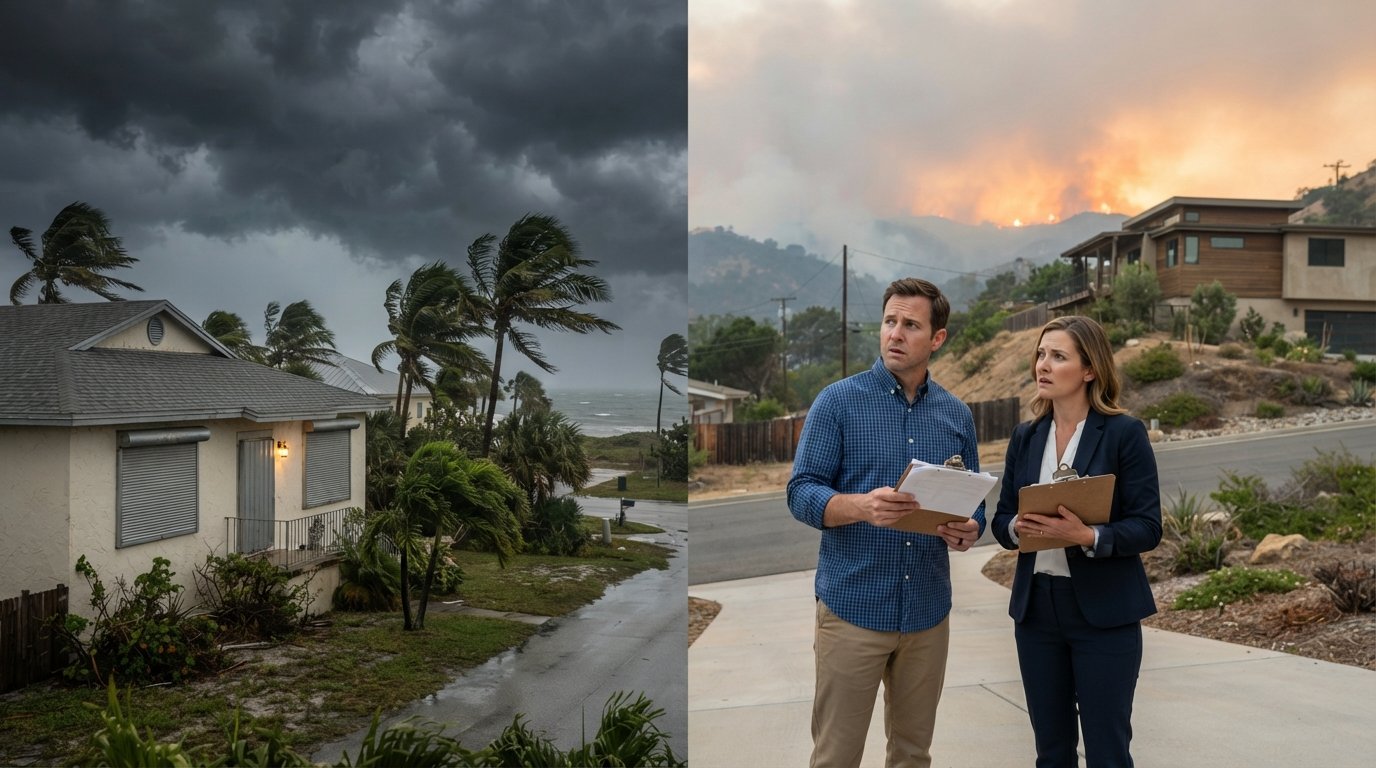
A single storm surge or a wind-driven ember can erase years of equity in hours. If you own a home in a hurricane zone or a wildfire corridor, your insurance policy is not just a safety net; it is the financial difference between rebuilding and walking away. Yet the rules in these high-risk areas are different from the standard homeowners policy most people know. Deductibles are higher, exclusions are broader, and carriers are pickier about which homes they will cover. This guide explains exactly what to expect from home insurance in hurricane and wildfire zones what to expect from your policy, your lender, and your options when the standard market says no.
Why High-Risk Zones Play by Different Rules
Insurance is a business of pricing risk. When a carrier looks at a coastal county or a hillside neighborhood adjacent to federal wildland, it sees a statistical probability of catastrophic loss that is far higher than in a landlocked suburb. To stay solvent, insurers respond in three ways: they charge more, they shift more of the initial loss to you through special deductibles, and they limit what they will cover. Understanding this triage is the first step to shopping intelligently.
Regulators allow insurers to use catastrophe models that project hurricane wind speeds, storm surge, and wildfire spread. Those models are why two homes five miles apart can see quotes that differ by thousands of dollars. Carriers also buy reinsurance (insurance for insurers), and the cost of that backstop flows directly into your premium. In wildfire states, insurers now weigh vegetation density, roof material, and access road width as heavily as they weigh square footage.
What this means for you is simple: you cannot assume a standard HO-3 policy will behave the way it does in a low-risk state. You need to read the declarations page, ask about named-storm and wildfire endorsements, and understand that the coverage you need may come from more than one policy.
Separate Deductibles: The Hidden Cost of Coastal and Fire Country Living
The single biggest surprise for homeowners in hurricane and wildfire zones is the percentage deductible. A standard policy might carry a flat $1,000 deductible for a kitchen fire. But for a named hurricane or a wildfire event, many carriers apply a deductible calculated as a percentage of your dwelling coverage, typically between 1% and 5%, and sometimes higher in the most exposed areas.
Run the math before you buy. On a home insured for $400,000, a 2% hurricane deductible means you pay the first $8,000 of damage out of pocket. A 5% wildfire deductible means $20,000. These are not rare edge cases; they are standard contract terms in high-risk regions, and they apply separately from your all-other-perils deductible. Some policies also trigger a wind/hail deductible that is distinct from the hurricane deductible.
Here is what to check on every quote in a catastrophe zone:
- Named-storm trigger: Does the deductible apply when a storm is named by the National Hurricane Center, or only when a hurricane warning is issued for your county?
- Wildfire trigger: Is the higher deductible triggered by a formal evacuation order, a declared disaster, or any fire within a certain distance?
- Dollar cap: Some policies cap the percentage deductible at a maximum dollar amount; ask whether yours does.
- Buy-back options: A few carriers let you purchase a lower percentage deductible for an added premium; compare that cost against the out-of-pocket exposure.
Budget for the deductible the way you budget for property taxes. If you cannot absorb a $10,000 or $20,000 hit after a disaster, a higher-premium policy with a lower percentage deductible may be the more responsible choice. And remember that your mortgage lender may have its own requirements about maximum deductibles, so confirm before you switch.
Flood Is Almost Never Included: Plan for a Separate Policy
Standard homeowners policies exclude flood, and in hurricane zones that exclusion is the most consequential gap in your protection. Storm surge, rising water, and even mudflow are typically excluded. Wind-driven rain that enters through a damaged roof may be covered, but water that rises from the ground is not. This distinction drives millions of claim disputes every year.
If you live in a FEMA-designated Special Flood Hazard Area and carry a federally backed mortgage, your lender will require flood insurance. But the requirement is a floor, not a ceiling. Homes outside the high-risk zone flooded in record numbers during recent hurricanes, and roughly a quarter of all flood claims come from properties outside mapped high-risk areas. Do not let a lender's minimum decide your exposure.
Flood policies are sold through the National Flood Insurance Program or through private carriers. Private flood insurance has expanded significantly and can offer higher coverage limits, replacement cost coverage on contents, and loss-of-use benefits that the federal program may not match. Compare both before you decide. In wildfire zones, flood risk often rises after a burn scar, because scorched soil repels water; that is another reason not to skip flood coverage just because you live on a hill.
When the Standard Market Says No: FAIR Plans, Residual Markets, and Surplus Lines
In the hardest-hit coastal and wildfire counties, major carriers have paused new business, non-renewed policies, or withdrawn entirely. If you cannot find a standard carrier, you still have options, but you need to understand what each one is.
FAIR plans and state insurers of last resort. Most coastal and wildfire states operate a residual market, often called a FAIR plan (Fair Access to Insurance Requirements) or a beach and windstorm pool. These programs exist to provide basic property coverage when the voluntary market will not. They typically cover fire, wind, and vandalism but may exclude liability, theft, and water damage. They are a backstop, not a full replacement for a standard policy, and many homeowners pair a FAIR plan with a separate difference-in-conditions (DIC) policy to fill the gaps.
Surplus lines carriers. These are insurers that are not licensed in your state but are permitted to write coverage for risks the admitted market will not take. Surplus lines policies are not backed by state guaranty funds, so you should verify the carrier's financial rating before signing. They can be expensive, but they are often the only option for high-value homes in extreme wildfire zones.
State-specific mitigation programs. Several states offer grants or credits for hardening your home, and some require insurers to recognize those upgrades. Ask your state insurance department whether a mitigation inspection or certificate could make you eligible for a residual market policy or a discount.
If you are comparing options and feel overwhelmed, a resource like InsuranceShopping.com can help you understand how these programs fit together and what questions to ask before you commit.
Mitigation Credits: Lower Your Premium by Hardening Your Home
Insurers increasingly reward homeowners who reduce their risk. In hurricane zones, that means impact-rated windows, storm shutters, a reinforced garage door, and a roof rated to withstand high wind. In wildfire zones, it means a Class A fire-rated roof, ember-resistant vents, and defensible space cleared around the structure. These upgrades can lower your premium, and in some cases they are the difference between getting a policy and being declined.
Before you spend money, ask your carrier or agent for the specific mitigation schedule it uses. Many insurers publish checklists, and some offer free inspections. A documented wind mitigation inspection in a coastal state can produce meaningful discounts on the wind portion of your premium. In wildfire states, a home hardening assessment can qualify you for credits and may be required for admission to a residual market program.
Keep receipts and inspection reports. When you shop for coverage, you will need to prove the upgrades exist. If you are preparing to request quotes, our guide on what information is needed for a home insurance quote walks through the documents and details carriers typically request, including mitigation documentation.
How Carriers Assess Risk by ZIP Code and What It Means for Your Quote
Your ZIP code is one of the strongest predictors of your home insurance premium in a catastrophe zone. Carriers use territory ratings that group neighborhoods by wildfire hazard severity, hurricane wind speed probability, and proximity to the coast. A move of a few miles inland, or to a different side of a ridge, can change your rate dramatically.
This is why two identical homes can receive quotes that differ by 50% or more. It also explains why your neighbor's rate is not a reliable benchmark. When you request quotes, expect to provide your exact address, the year of construction, roof type and age, exterior wall material, and whether you have a fire hydrant within a certain distance. In wildfire zones, carriers may also ask about the slope of your lot, the width of your access road, and the vegetation within 100 feet of the structure.
If you are shopping, get quotes from multiple carriers and compare the deductible structure, not just the premium. A low premium with a 5% wildfire deductible can be far more expensive in a real loss than a higher premium with a 1% deductible. Also ask whether the carrier uses replacement cost or actual cash value for the dwelling; in high-risk zones, some policies shift to actual cash value for roof claims, which can leave you underinsured.
Finally, confirm that your policy includes adequate building code upgrade coverage. After a major disaster, local codes often change, and rebuilding to current standards can cost more than your dwelling limit. Law and ordinance coverage helps close that gap, and it is worth asking about in every hurricane and wildfire quote.
The bottom line for homeowners in hurricane and wildfire zones is that insurance requires active management. Know your percentage deductibles, carry separate flood coverage, understand the residual market options, document your mitigation upgrades, and compare quotes with the same scrutiny you would apply to any major financial decision. The market in these regions is challenging, but with the right preparation and the right questions, you can protect both your home and your financial footing.