Liability vs Full Coverage Car Insurance: What Is the Difference?
Liability vs full coverage car insurance: learn what each covers, when each makes sense, and how deductibles differ so you avoid surprise repair bills.
By Quinn Hayes
Choosing car insurance can feel like navigating a maze of jargon. Two terms dominate the conversation: liability coverage and full coverage. Drivers often assume full coverage is simply better, but the right choice depends on your vehicle, your budget, and your state's laws. Understanding the difference between liability and full coverage car insurance is essential for making an informed decision that protects your finances without overpaying for unnecessary protection. This guide breaks down exactly what each type covers, when each makes sense, and how deductibles work differently for each.
What Is Liability Coverage and What Does It Pay For?
Liability coverage is the foundation of almost every auto insurance policy in the United States. It is the coverage that most states require by law, and it protects you when you are at fault in an accident that injures someone else or damages their property. Liability insurance does not cover your own injuries or your own vehicle; it covers the other party's losses.
Liability coverage is typically split into two components. Bodily injury liability pays for medical expenses, lost wages, and legal fees if you injure someone else in an accident. Property damage liability pays to repair or replace the other person's vehicle or other property, such as a fence or mailbox. Most states require minimum levels of both, though the required amounts vary widely. For example, some states require as little as $25,000 per person for bodily injury, while others mandate significantly higher limits.
It is important to understand that liability coverage does not have a deductible. When you file a liability claim, your insurer pays up to your policy limit without you having to pay anything out of pocket first. However, if the damages exceed your limit, you are personally responsible for the difference. This is why many financial experts recommend purchasing liability limits higher than your state's minimum requirements.
What Does Full Coverage Car Insurance Actually Mean?
Here is a surprising fact: full coverage is not a legal term, and no state requires it. Full coverage is simply an industry shorthand for a policy that includes liability coverage plus collision coverage and comprehensive coverage. When people ask about the difference between liability and full coverage car insurance, they are really asking whether they need the added protection that collision and comprehensive provide.
Collision coverage pays to repair or replace your own vehicle if it is damaged in a collision with another vehicle or object, regardless of who is at fault. Comprehensive coverage pays for damage to your vehicle from causes other than collisions, such as theft, vandalism, fire, hail, flooding, or hitting an animal. Together, these two coverages protect your vehicle in a much broader range of situations than liability alone.
Unlike liability coverage, both collision and comprehensive come with deductibles. A deductible is the amount you agree to pay out of pocket before your insurance kicks in. For example, if you have a $500 deductible and your car sustains $3,000 in collision damage, you pay $500 and your insurer covers the remaining $2,500. Choosing a higher deductible typically lowers your premium, while a lower deductible means you pay more upfront but less at the time of a claim.
Liability vs Full Coverage: Key Differences at a Glance
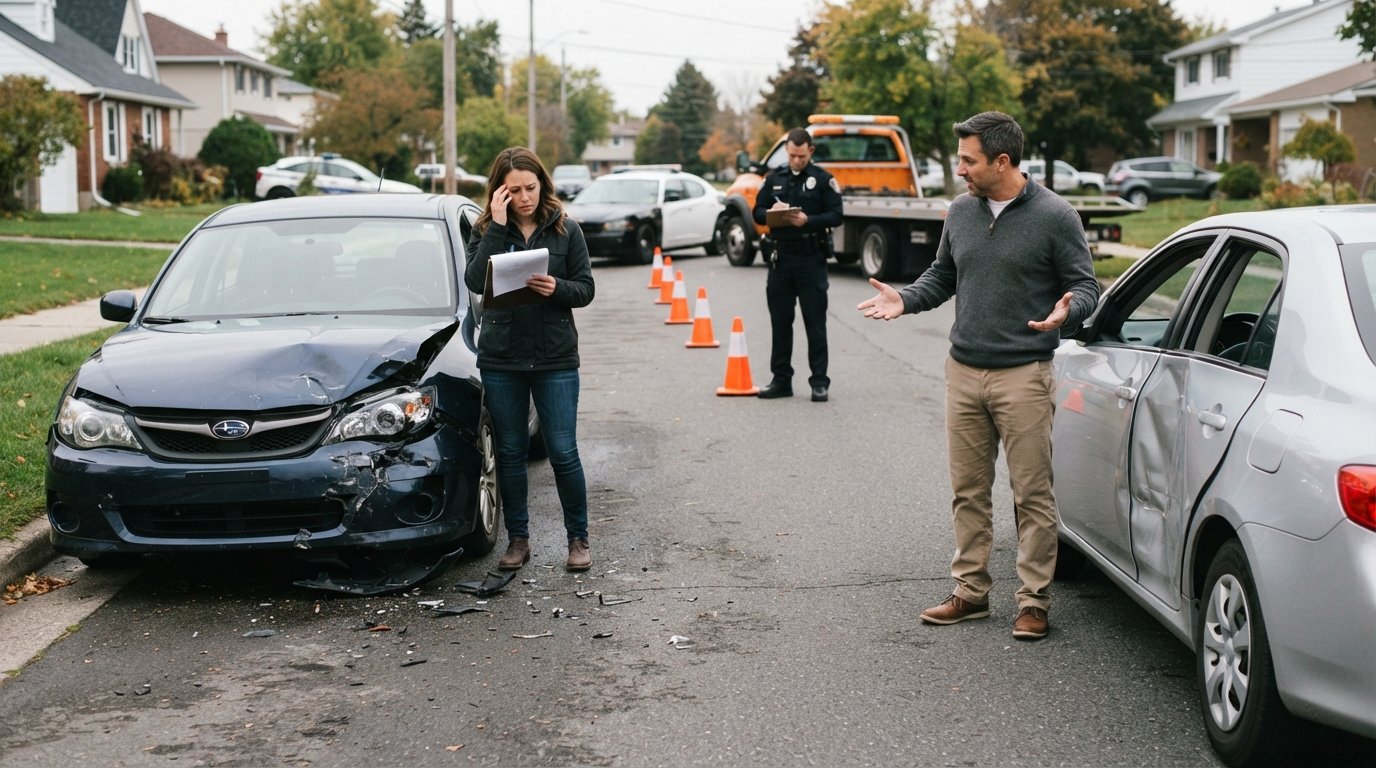
To clarify the distinction, consider how each type of coverage responds in common scenarios. If you rear-end another driver, liability pays for their repairs and medical bills, while collision pays for your own car's damage. If a hailstorm dents your hood, comprehensive covers it, but liability pays nothing toward your vehicle. If your car is stolen, only comprehensive responds.
Here are the main differences between liability and full coverage car insurance:
- What it protects: Liability covers other people and their property; full coverage adds protection for your own vehicle.
- Deductibles: Liability has no deductible; collision and comprehensive each carry a deductible you choose.
- Cost: Liability-only policies are significantly cheaper; full coverage costs more but provides broader protection.
- Legal requirements: Liability is required in nearly every state; full coverage is optional unless your lender or lessor requires it.
- Claims scenarios: Liability responds when you are at fault for injuring others; full coverage responds when your own vehicle is damaged or stolen.
Understanding these differences helps you evaluate quotes accurately. A liability-only policy may seem like a bargain until you realize that a single at-fault accident could leave you paying thousands out of pocket to repair your own car. Conversely, full coverage on an older, low-value vehicle may cost more in premiums than the car is worth.
When Does Each Option Make Sense?
The right choice depends on several factors, including your vehicle's value, whether you have a loan or lease, and your personal financial situation. Full coverage is almost always required if you are leasing a vehicle or paying off an auto loan. Lenders and leasing companies want to protect their investment, so they mandate collision and comprehensive coverage until the loan is satisfied or the lease ends.
If you own your car outright and it has a low market value, liability-only coverage may be the more economical choice. A common rule of thumb is that if your annual full coverage premium exceeds 10 percent of your car's value, the extra cost may not be justified. For example, if your car is worth $4,000 and full coverage costs $800 per year, you might be better off saving that money and self-insuring for collision and comprehensive risks.
Full coverage makes the most sense when your vehicle is new or valuable, when you could not easily afford to repair or replace it after an accident, or when you want the peace of mind that comes with broader protection. Drivers who live in areas with high rates of theft, severe weather, or wildlife collisions may also find comprehensive coverage particularly valuable.
How Deductibles Work Differently for Each Coverage Type
One of the most practical differences between liability and full coverage is how deductibles apply. Liability coverage has no deductible, so your insurer pays covered claims up to your policy limit immediately. This means that if you cause an accident and injure someone, you do not need to come up with cash before your insurance responds.
Collision and comprehensive coverage, by contrast, each carry their own deductible. You choose these amounts when you purchase your policy, and they can be the same or different. A higher deductible lowers your monthly premium but increases your out-of-pocket cost when you file a claim. A lower deductible does the opposite. Many drivers choose a $500 or $1,000 deductible as a balance between affordable premiums and manageable claim costs.
It is also worth noting that filing a collision or comprehensive claim may affect your premium, while a liability claim can have an even greater impact because it involves injury to others. Some insurers offer accident forgiveness or vanishing deductibles as incentives, so it is worth asking about these features when comparing quotes.
How to Compare Liability and Full Coverage Quotes
Comparing quotes for liability-only versus full coverage is the best way to see the real-world cost difference for your specific situation. Rates vary significantly based on your ZIP code, driving record, vehicle, age, and the carrier you choose. That is why it is important to shop around and compare multiple offers before committing.
When requesting quotes, be prepared to provide basic information such as your vehicle's make, model, and year, your driving history, and your desired coverage levels. You should also decide on a deductible for collision and comprehensive coverage if you are considering full coverage. Remember that plan availability and rates vary by ZIP code and carrier, so the quotes you receive will reflect your local market.
For a convenient way to compare quotes from multiple providers, you can use a resource like InsuranceShopping.com, which connects consumers with insurance providers and agents. Whether you are leaning toward liability-only or full coverage, getting quotes from several sources helps you make a confident decision.
Common Misconceptions About Liability and Full Coverage
Many drivers misunderstand what full coverage actually includes. Some assume it means "everything is covered," but full coverage still has exclusions, limits, and deductibles. For example, full coverage does not pay for routine maintenance, wear and tear, or mechanical breakdowns. It also does not cover injuries to you or your passengers unless you add medical payments or personal injury protection coverage.
Another common misconception is that liability coverage protects your own vehicle. It does not. If you carry only liability insurance and you are at fault in an accident, you will pay out of pocket to repair your own car. Similarly, if your car is damaged by something other than a collision, such as a falling tree branch, liability will not help.
Finally, some drivers believe that full coverage is always required by law. It is not, except when a lender or lessor mandates it. State minimum requirements typically include only liability coverage, and sometimes uninsured motorist coverage or personal injury protection, depending on the state.
Frequently Asked Questions About Liability vs Full Coverage
Is full coverage always better than liability-only?
Not necessarily. Full coverage costs more, and if your vehicle is old or low in value, the extra premium may outweigh the benefits. The right choice depends on your car's value, your financial cushion, and whether you have a loan or lease.
Does full coverage include liability?
Yes. Full coverage is not a separate policy; it is a combination of liability, collision, and comprehensive coverage. You cannot have full coverage without liability coverage.
What happens if I drop full coverage and later need it?
You can typically add collision and comprehensive coverage back to your policy at any time, though your insurer may require an inspection or charge a higher rate if there has been a lapse. It is wise to review your coverage annually as your car's value changes.
Deciding between liability and full coverage car insurance comes down to understanding what each protects and weighing that protection against the cost. Liability coverage is your legal safety net for injuries and damage you cause to others, while full coverage adds a layer of protection for your own vehicle. By evaluating your car's value, your loan or lease requirements, and your budget, you can choose the policy that fits your needs and drives with confidence. For personalized guidance and quote comparisons, InsuranceAdvisers.com can connect you with licensed agents who understand your local market and can help you explore your options.