What a Licensed Insurance Agent Does During the Quote Process
See what a licensed insurance agent actually does during the quote process, from verifying licensing to comparing carriers and explaining compensation.
By Alice Keller
You have probably seen the ads: enter your ZIP code, click a button, and wait for the phone to ring. But what happens after that? Many shoppers hesitate to share personal details because they are not sure who is on the other end of the line or what that person will actually do with the information. Understanding the role of a licensed insurance agent during the quote process removes the mystery and helps you use that conversation to your advantage. Whether you are shopping for auto, home, health, life, or Medicare coverage, knowing what a licensed agent can and cannot do will save you time and protect your privacy.
The First Step: Verifying Licensing and Authority
Before an agent ever asks for your date of birth or driving record, a legitimate professional will be prepared to prove they are authorized to sell insurance in your state. Insurance is regulated at the state level, and every agent must hold an active license for the specific lines of coverage they discuss. A life insurance license does not permit someone to sell auto policies, and a health license does not automatically cover Medicare products. During the quote process, a licensed agent should be able to provide their name and license number, and many will offer to let you verify that number through your state department of insurance website. This is not an unusual request; it is a sign that you are dealing with a compliant professional.
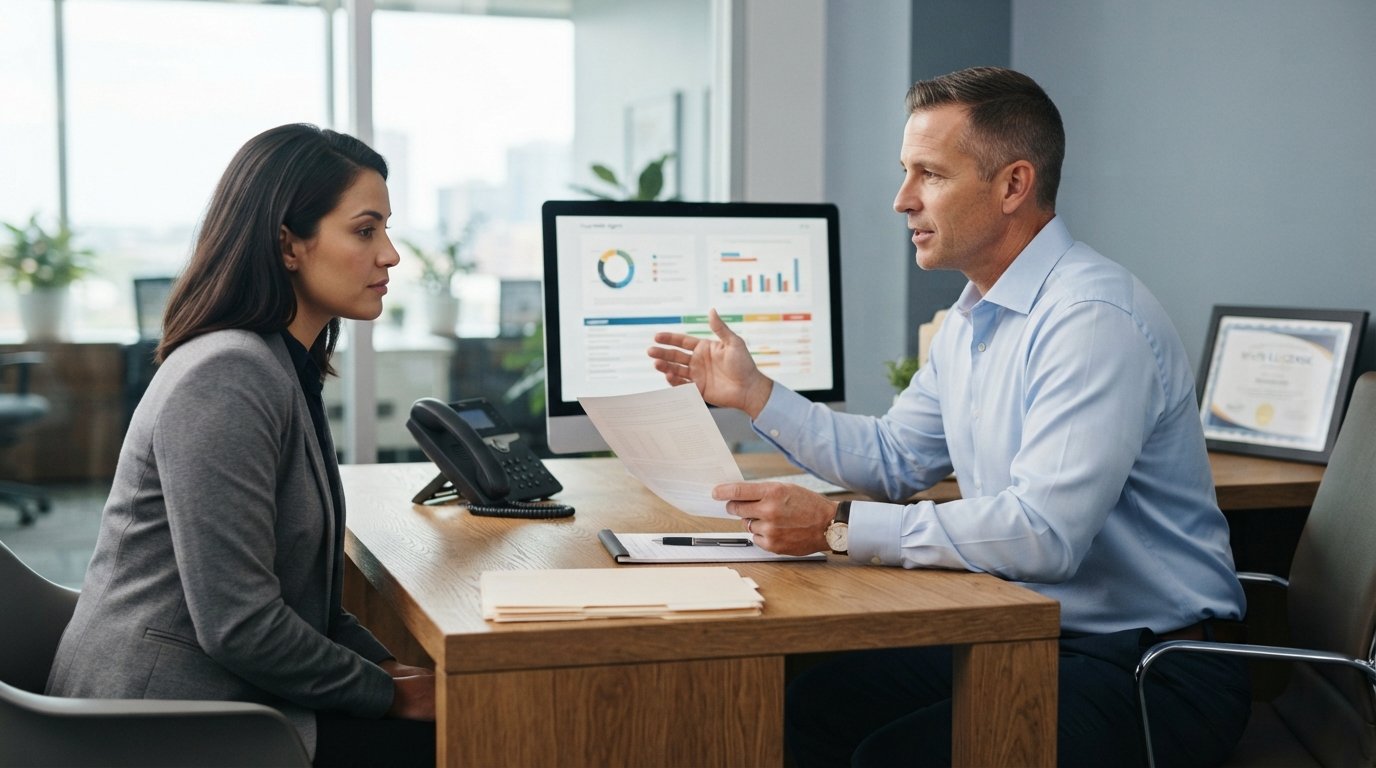
What does a licensed insurance agent do during the quote process that an unlicensed representative cannot? The answer is simple: they can legally discuss specific policy terms, advise on coverage limits, and submit your application to a carrier. Unlicensed staff may answer basic questions and take your information, but they cannot recommend a policy or negotiate on your behalf. If someone pressures you for sensitive data before identifying their license status, that is a red flag. A reputable agent will welcome the question and may even volunteer the information first.
Captive Versus Independent Agents: How Many Quotes You Actually Get
The type of agent you speak with determines how many options you will see. A captive agent works exclusively for one insurance company. They can quote only that company's products, which means their recommendation is limited by design. An independent agent, by contrast, contracts with multiple carriers and can quote several companies during a single conversation. This distinction matters because the same driver or homeowner can receive wildly different rates from different insurers based on each company's underwriting appetite. An independent agent can compare those offers side by side, while a captive agent can only explain why their single company is the best fit.
Neither model is inherently dishonest, but you should know which one you are dealing with before you invest time in the quote process. Ask directly: "Are you captive or independent, and how many carriers can you quote for me today?" A captive agent should answer honestly and explain the value of their company's products. An independent agent should be able to name the carriers they represent and explain any limitations, such as a carrier that does not write policies in your ZIP code. This is also a good moment to ask whether the agent can quote bundled policies, since bundling auto and home coverage often produces savings that a single-line quote would miss.
If you prefer to start your research before speaking with anyone, resources like InsuranceShopping.com offer educational guides and comparison tools that explain how different policy types work. That background knowledge makes the agent conversation more productive because you can ask specific questions instead of relying entirely on the agent's summary.
Gathering the Right Information for an Accurate Quote
A quote is only as good as the data behind it. During the quote process, the agent's job is to collect enough detail to match you with accurate rates and appropriate coverage. For auto insurance, that means vehicle make and model, annual mileage, driving history, and the garaging address. For home insurance, agents ask about square footage, roof age, construction type, and claims history; our guide on what information is needed for a home insurance quote walks through those details in depth. Health and life insurance quotes require age, tobacco use, household size, and sometimes medical history, while Medicare quotes depend on eligibility status and prescription needs.
Here is what a licensed agent typically does with that information during the quote process:
- Enters your details into each carrier's rating system to generate real, carrier-specific estimates rather than generic averages.
- Compares coverage levels, deductibles, and out-of-pocket limits across the options returned.
- Flags any underwriting concerns, such as a recent claim or a health condition, that could affect eligibility or pricing.
- Explains which discounts you qualify for and how adjusting a deductible would change the premium.
- Documents the quote details so you have a written record to review later.
Notice what is not on that list: binding coverage or promising a final rate. A quote is an estimate based on the information you provide, and the final premium can change after underwriting review. An honest agent will say this clearly rather than implying that the number on the screen is guaranteed. If you are comparing multiple agents, ask each one whether the quoted premium is subject to change and what factors could cause it to move.
How Agents Are Paid and What It Means for Their Recommendations
Compensation is one of the least discussed parts of the quote process, yet it directly affects the advice you receive. Most agents earn a commission when you purchase a policy, paid by the insurance carrier rather than by you directly. Commission rates vary by carrier and by policy type, and some carriers pay higher commissions than others. A captive agent's compensation is tied to a single company, so their incentive is to place you with that company. An independent agent may earn different commissions depending on which carrier you choose, which creates at least a theoretical incentive to steer you toward higher-paying products.
This does not mean agents are dishonest, but it does mean you should ask questions. A straightforward agent will explain how they are paid and whether their recommendation changes based on compensation. You can also ask whether the agent receives any bonus or incentive for placing a certain volume of business with a particular carrier. Fee-based agents charge you directly and may offer a broader range of options, though this model is less common in personal lines. Understanding the compensation structure helps you evaluate whether the recommendation is based on your needs or the agent's revenue.
What Agents Cannot Do: Rate Guarantees and Instant Policy Issuance
Shoppers often expect that a quote conversation ends with a policy in hand. In reality, a licensed agent cannot guarantee a rate or issue a policy on the spot in most cases. The quote is an estimate, and the carrier's underwriting department makes the final decision. For auto and home insurance, underwriting may involve a motor vehicle report, a claims history check, or a property inspection. For life and health insurance, medical underwriting can take days or weeks, and the final premium may differ from the initial quote if the carrier discovers information that changes your risk profile.
A licensed agent also cannot bind coverage without proper authorization and payment, and even then, binding rules vary by carrier and state. If an agent promises that you are "covered as of right now" without collecting payment or submitting a formal application, ask for written confirmation. Legitimate agents will explain the difference between a quote, an application, and a bound policy. They will also tell you when coverage actually takes effect, which is often not the moment you say yes.
Another important limitation: agents cannot provide medical advice or tell you which Medicare plan is "best" in a clinical sense. They can explain plan benefits and costs, but the decision about your care belongs to you and your doctor. Similarly, agents cannot waive underwriting requirements or promise that a claim will be paid. They can explain how claims work, but the claims department makes its own determination.
Questions to Ask Before Sharing Sensitive Details
You should never feel pressured to hand over your Social Security number, medical records, or banking information before you are comfortable with the agent and the process. A few simple questions can establish trust and clarify what will happen with your data. Ask whether the agent is licensed in your state, whether they are captive or independent, and how many carriers they will quote. Ask how your information will be stored, whether it will be shared with other parties, and whether you can opt out of marketing communications. A professional agent will answer these questions without hesitation and will not make you feel foolish for asking.
It is also reasonable to ask for a written summary of the quote before you agree to anything. The summary should include the carrier name, coverage limits, deductibles, premium, and any exclusions. If the agent cannot provide that in writing, consider it a warning sign. Finally, ask what happens after the quote: will the agent follow up, will the carrier contact you directly, and what is the timeline for a decision? Knowing the next steps prevents surprises and keeps the process moving.
Using the Quote Conversation to Your Advantage
The quote process is not just a sales pitch; it is an opportunity to learn how insurance works for your specific situation. A good agent will explain why one carrier is cheaper than another, which coverage limits matter for your assets, and how a claim would affect your future premiums. They will also tell you when a cheaper policy is a bad idea because it leaves you underinsured. Use the conversation to ask about gaps in coverage, such as whether your auto policy includes rental reimbursement or whether your home policy covers flooding, which is typically excluded.
Remember that plan availability and rates vary by ZIP code and carrier, so the options you see are specific to your location and profile. No website or agent can guarantee a rate, payment amount, or issued policy. What a licensed agent can do is help you understand the trade-offs, compare legitimate options, and avoid common mistakes. That is the real value of the quote process: not a magic number, but a clearer picture of what you are buying and why.
When you are ready to start comparing, keep these expectations in mind and ask the right questions. A licensed agent should be a guide, not a pressure point, and the best quote process ends with you feeling informed rather than rushed.