What Does Home Insurance Dwelling Coverage Cover?
Dwelling coverage pays to rebuild your home's structure after a covered loss. Learn what it includes, how limits are set, and common exclusions to avoid gaps.
By Patrick Parker
Your home is likely your largest financial asset, and the dwelling portion of your homeowners policy is the shield that protects its physical structure. But what does home insurance dwelling coverage cover, exactly? If a fire tears through your kitchen or a hailstorm shreds your roof, dwelling coverage is the part of your policy that pays to rebuild the house itself. Understanding this coverage, how limits are set, and what it excludes is essential for every homeowner who wants to avoid a financial shock after a disaster.
At its core, dwelling coverage (often listed as Coverage A on a standard HO-3 policy) pays to repair or rebuild the physical structure of your home, including attached features like a garage, deck, or porch. It does not cover your personal belongings, liability claims, or temporary living expenses; those are handled by other sections of your policy. Getting the dwelling limit right is one of the most important decisions you will make when shopping for home insurance. This guide breaks down exactly what dwelling coverage protects, how insurers calculate limits, common gaps, and when you should update your policy.
What Dwelling Coverage Actually Pays For
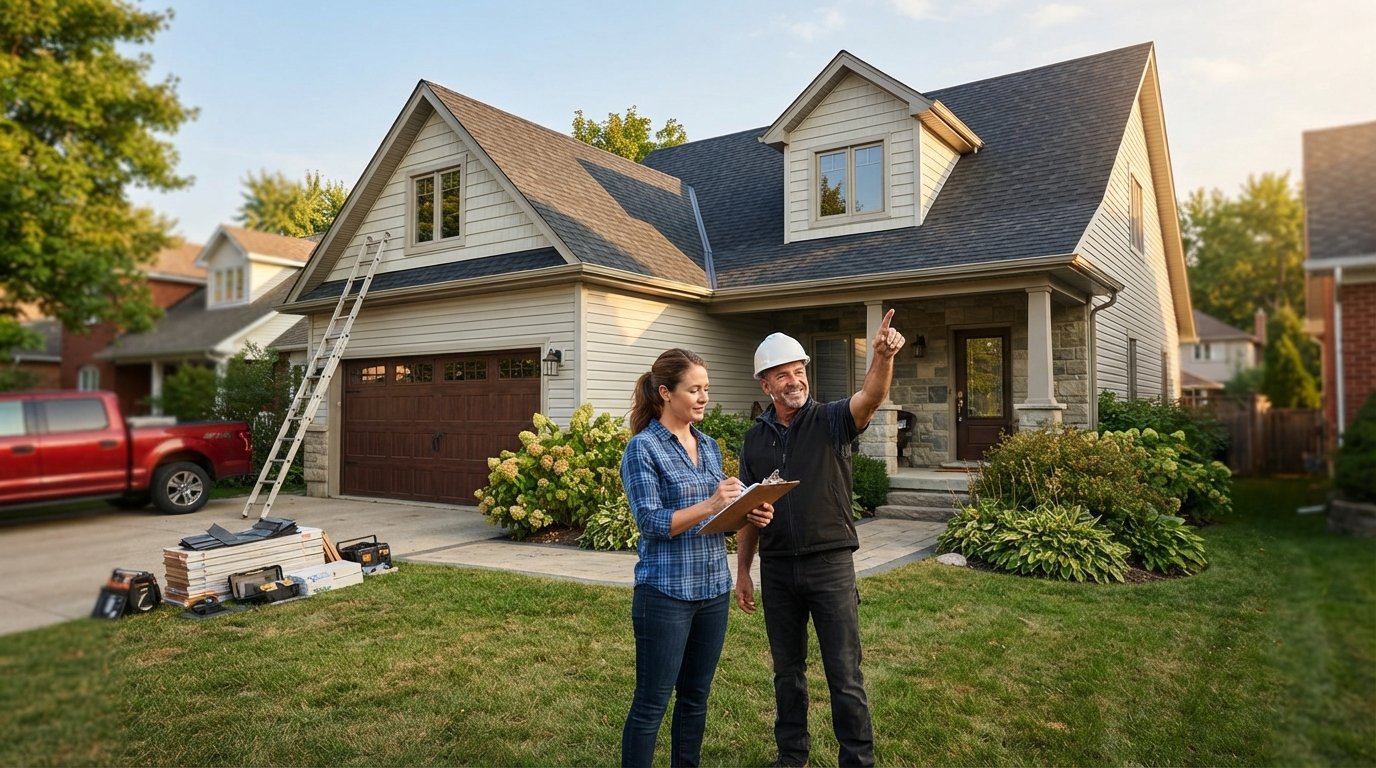
Dwelling coverage is the foundation of your homeowners policy. It pays to repair or replace the structure of your home if it is damaged by a covered peril, such as fire, windstorm, hail, lightning, vandalism, or a burst pipe. The coverage applies to the house itself and to any structures physically attached to it. That means the framing, roof, siding, foundation, built-in appliances, and permanently installed fixtures like a water heater or furnace are all typically included.
Attached features are a key part of the equation. A connected garage, a covered porch, a deck, or a fence that is attached to the house usually falls under dwelling coverage. Detached structures, such as a freestanding shed or a detached garage, are often covered under a separate "other structures" provision (Coverage B), which typically carries a limit equal to about 10 percent of your dwelling limit. Knowing the difference prevents surprises when you file a claim.
Here is a quick breakdown of what dwelling coverage typically includes:
- The main house structure: walls, roof, floors, foundation, and framing.
- Attached structures: garage, porch, deck, or carport connected to the home.
- Built-in fixtures and permanently installed systems: plumbing, electrical wiring, HVAC, water heater, and kitchen cabinets.
- Materials and labor to rebuild or repair after a covered loss, up to your policy limit.
Importantly, dwelling coverage does not pay for your furniture, electronics, clothing, or other personal property. That is handled by personal property coverage (Coverage C). Nor does it cover liability if someone is injured on your property; that falls under personal liability coverage (Coverage E). And it does not cover additional living expenses if your home becomes uninhabitable; that is Coverage D. Each piece of your policy serves a distinct purpose, and dwelling coverage is strictly about the physical structure.
How Dwelling Limits Are Set: Replacement Cost vs. Market Value
One of the most common misunderstandings among homeowners is that dwelling coverage should equal the market value of the home. In reality, insurers base dwelling limits on the cost to rebuild the structure, not on what the home would sell for. Market value includes the land, location, and recent sale prices of comparable homes, none of which matter when you are replacing a roof or rebuilding walls. Replacement cost focuses on materials, labor, and debris removal at current local prices.
Most standard policies use replacement cost coverage for the dwelling, meaning the insurer pays to rebuild your home with materials of similar kind and quality, without deducting for depreciation. Some policies offer extended replacement cost, which provides an additional 10 to 25 percent above the stated limit if construction costs spike. Actual cash value (ACV) coverage, by contrast, deducts depreciation and pays less, so it is less common for dwelling coverage but may appear on older homes or lower-cost policies.
To set an accurate dwelling limit, insurers use replacement cost estimators that factor in square footage, construction type, roof material, local labor rates, and building code requirements. You can help ensure accuracy by providing details about renovations, upgrades, and unique features. If you are unsure what information you need to gather, our guide on what information is needed for a home insurance quote walks through the key details insurers request.
Underinsuring your dwelling is a serious risk. If your limit is too low, you may face a coinsurance penalty or simply run out of money before the rebuild is complete. Overinsuring wastes premium dollars. A professional replacement cost estimate, reviewed every few years, is the best way to strike the right balance.
Common Exclusions: Floods, Earthquakes, and Wear and Tear
Even the broadest homeowners policy does not cover everything. Dwelling coverage is subject to exclusions that every homeowner should understand before a loss occurs. The most significant exclusion is flood damage. Standard home insurance does not cover flooding from rising water, storm surge, or overflowing rivers. Flood coverage must be purchased separately, typically through the National Flood Insurance Program or a private insurer.
Earthquake damage is also excluded on most standard policies. In seismically active regions, homeowners need a separate earthquake endorsement or policy. Other common exclusions include:
- Normal wear and tear, deterioration, and insect or rodent damage.
- Damage from poor maintenance or faulty workmanship.
- Sewer backup, unless a backup endorsement is added.
- Damage caused by intentional acts or neglect.
- Ordinance or law costs, unless extended replacement cost or building code coverage is included.
These exclusions matter because they can leave you with a damaged structure and no coverage. For example, a slow leak that rots framing over years is typically considered wear and tear, not a sudden covered peril. Similarly, a flood that rises into your home is not a windstorm claim, even if a storm caused the flooding. Review your policy's exclusions page carefully and ask your agent about endorsements that fill common gaps.
It is also worth noting that dwelling coverage applies only to covered perils listed in your policy. An open-peril policy (like HO-3) covers all risks except those explicitly excluded, while a named-peril policy covers only the events listed. Most standard homeowners policies are open-peril for the dwelling, which is broader protection, but exclusions still apply.
When to Review and Update Your Dwelling Coverage
Dwelling coverage is not a set-it-and-forget-it number. Life changes and market shifts can leave your limit out of sync with reality. The most common trigger is a renovation. If you add a room, finish a basement, replace a roof with higher-grade materials, or install a pool, your rebuild cost rises. Failing to update your dwelling limit means you could be underinsured when you need to rebuild.
Local construction costs also fluctuate. After a major disaster or during a building boom, labor and material prices can spike. If your policy has a standard replacement cost limit, you may not have enough to rebuild at today's prices. Extended replacement cost coverage provides a cushion, but it is still wise to review your limit annually. Insurers often adjust dwelling limits automatically for inflation, but those adjustments may not keep pace with local cost increases.
Here is a simple framework for keeping your dwelling coverage current:
- Review your policy limit every year, ideally before renewal.
- Update your insurer after any major renovation, addition, or upgrade.
- Ask about extended replacement cost or building code coverage if your home is older.
- Re-run a replacement cost estimator if local construction costs have risen sharply.
- Consider a professional inspection or appraisal if you have made significant changes.
Taking these steps helps ensure that if disaster strikes, your dwelling coverage is enough to rebuild your home without draining your savings. It also positions you to compare quotes accurately when you shop around. Speaking of shopping, comparing policies from multiple carriers is one of the best ways to find competitive rates for the dwelling coverage you need. You can start by using a comparison tool like QuoteComparison to see how different insurers price similar coverage in your area.
Dwelling Coverage vs. Other Policy Components
To fully understand what home insurance dwelling coverage covers, it helps to see how it fits alongside the other parts of your policy. Personal property coverage protects your belongings, both inside and outside the home, up to a stated limit. Liability coverage protects you financially if someone is injured on your property or if you accidentally damage someone else's property. Additional living expenses coverage pays for hotel stays, meals, and other costs if your home is uninhabitable after a covered loss.
Each component has its own limit, and the dwelling limit is usually the largest. A common mistake is assuming that a high personal property limit means the dwelling is well covered, or vice versa. In reality, you need to review each limit separately based on your possessions, your home's rebuild cost, and your risk tolerance. A licensed insurance agent can help you balance these limits so you are neither overinsured nor underinsured.
It is also important to note that dwelling coverage does not extend to land or to structures used for business purposes. If you run a home-based business with a detached workshop or inventory, you may need a separate business policy or endorsement. Similarly, high-value items like jewelry, art, or collectibles may need scheduled personal property coverage because standard personal property limits may be too low.
Key Takeaways for Homeowners
Dwelling coverage is the backbone of your homeowners policy, protecting the structure you live in and the attached features that make it a home. It pays to repair or rebuild after covered perils like fire, wind, hail, or vandalism, up to your policy limit. It does not cover floods, earthquakes, wear and tear, or your personal belongings. Setting the right limit requires a replacement cost estimate, not a market value guess, and that limit should be reviewed after renovations or when local construction costs rise.
Understanding these details puts you in a stronger position to shop for coverage, ask the right questions, and avoid nasty surprises at claim time. Whether you are buying your first home or reviewing an existing policy, take a few minutes to check your dwelling limit and confirm it matches today's rebuild costs. Your future self will thank you.